The Current State of Japan's Stablecoins — The World's First Jurisdiction for Stablecoin Legislation
Stablecoin Field — Stablecoin Stories Around the World #5 | Japan
I. Macro Policy: Japan's Specialized Stablecoin Legislation and Three-Tier Regulatory Framework
Japan became the world's first jurisdiction to enact dedicated stablecoin legislation. The revised Payment Services Act was passed by the National Diet in June 2022 and took effect in June 2023, defining stablecoins as electronic payment instruments and distinguishing them legally from cryptocurrencies like Bitcoin.
Regulatory Positions during Legislative Deliberations (Based on FSA documents and Financial Council meeting records, objectively paraphrased)
Regulators focused on mitigating run risks, reserve mismanagement, and smart contract vulnerabilities. They framed stablecoins as a complement to, rather than a replacement for, existing payment systems. Under licensed oversight and with strict safeguards for user funds, regulators selectively encourage stablecoins for their potential to boost settlement efficiency.
Four core provisions of the legislation:
- Restricted Issuer Eligibility: Domestic yen stablecoins may only be issued by licensed banks, trust companies, and Class 2 Fund Transfer Service Providers; crypto-native firms are prohibited from direct issuance.
- Mandatory Redemption Obligation: Issuers must guarantee users the right to redeem stablecoins at face value at any time.
- Evolving Reserve Asset Rules: Previously, all reserves had to be held in demand deposits. New rules effective June 2026 allow up to 50% of reserves to be allocated to low-risk, short-term Japanese government bonds. Interest generated from reserves accrues to the issuers; holders earn no interest.
-
Three-Tier Regulatory Architecture:
- Domestic Yen Stablecoin Issuance: Primarily for corporate B2B settlements, carrying a per-transaction cap of JPY 1 million under Class 2 licenses. Maruwa Logistics is rolling out its service regionally and in phases to comply with this cap.
- Distribution of Foreign Stablecoins: Operated by licensed intermediaries such as SBI VC Trade, requiring strict asset segregation and AML/KYC enforcement.
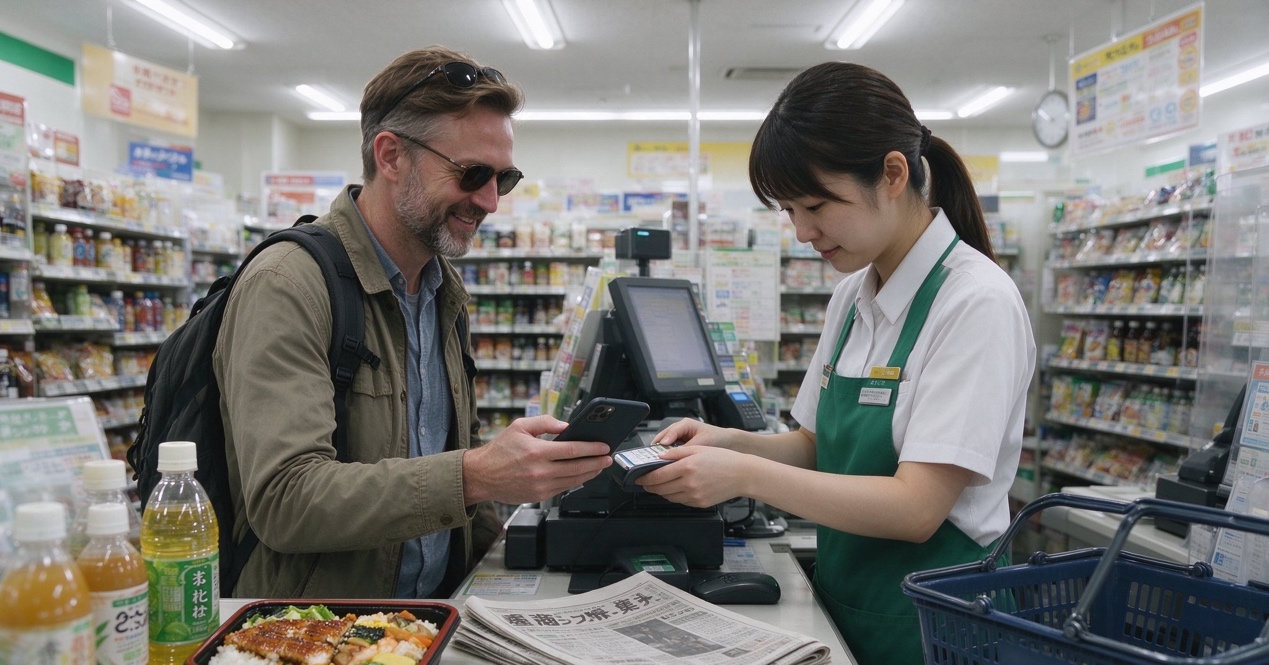
- Cross-Border Payment Rails for Inbound Tourists: Powered by HIVEX and Binance Pay. Tourists settle payments via PayPay QR codes, while merchants receive yen without holding any crypto assets.
While Japan is a pioneer in stablecoin legislation, its commercial adoption lags behind economies like the United States and Singapore. Japan launched consultations on stablecoin regulation back in 2019, and the Terra stablecoin collapse in 2022 accelerated the legislative timetable. The revised Payment Services Act cleared the Diet in June 2022, making Japan the first country globally to implement dedicated stablecoin rules. According to official documents from Japan's Financial Services Agency (FSA), the primary legislative goals are to mitigate risks such as stablecoin runs and reserve embezzlement, protect user assets, and accommodate blockchain payment innovation while maintaining strict safety guardrails. Regulators recognize stablecoins' potential to raise settlement efficiency yet classify them as electronic payment instruments subject to conventional financial supervision.
Although countering the dominance of US-denominated stablecoins was not cited as an official legislative objective, analyses by multiple financial media outlets and domestic institutions note that US stablecoins dominated nearly all on-chain settlement markets at the time. By establishing a compliant framework early, Japan successfully reserved room for domestic yen stablecoins, preventing the long-term monopolization of regional digital settlement tracks by US stablecoins. Japan also aimed to strengthen its voice in setting global stablecoin regulatory standards through this pioneering regime. This provides a valuable blueprint for other advanced economies. Historically, high regulatory barriers, a limited pool of authorized issuers, and a prolonged low-interest-rate environment dampened issuer incentives to promote adoption; however, recent rate hikes in Japan are expected to improve this outlook.
II. Industry Landscape: Tokenized Asset Integration, Agent Payment Exploration, Japan-US Stablecoin Comparison, Enterprise B2B Rollout, and Domestic Stablecoin Growth
2.1 Tokenization and Stablecoin Integration
Japan's stablecoin and tokenized asset initiatives remain at the testnet proof-of-concept (PoC) stage and are not commercially live, currently utilizing the trust-based stablecoin JPYSC as the settlement backbone. SBI, DigiFT, and Startale completed a PoC on testnets, enabling instant settlement for tokenized fund subscriptions and automated on-chain dividend disbursements via JPYSC.
Conceptually, stablecoins serve as the settlement currency for tokenized securities, funds, and other RWA (Real World Assets). However, regulators impose clear constraints: complex programmable logic remains confined to isolated test environments, and the large-scale deployment of autonomous execution contracts on mainnets is not currently permitted. Regulators prioritize stablecoin redemption safety and fear payout shocks stemming from smart contract flaws. Automated cash flow and redemption functions for tokenized assets are restricted to small-scale pilots and cannot yet be deployed at scale.
Core regulatory stance: Stablecoins settle tokenized assets, but the complex conditional programmability of the underlying assets is treated with extreme caution.
2.2 Agent Payment Development in Japan
Japan has no dedicated legislation for AI agent payments, a field still in the frontier research phase. Agent payments leverage stablecoins' programmable funds, enabling AI agents to execute transactions automatically under predefined rules. Relevant trials in Japan are confined to conceptual and small-scale testing, with no public commercial launch. Regulators permit simple machine-to-machine payments provided fund flows remain within licensed financial institutional frameworks. They maintain high caution regarding permissionless AI agents autonomously managing programmable stablecoin funds. In contrast, the United States has already delivered engineering deployments for the X402 protocol and agent wallets; Japan's progress largely remains at the policy discussion stage, with few practical applications.
2.3 Japan-US Stablecoin Comparison (Regulation and Use Cases)
Regulatory Framework
- Japan: The 2023 statute was enacted early. Yen stablecoin issuance is restricted to banks, trust firms, and Class 2 Fund Transfer Service Providers. Class 2 licenses carry a JPY 1 million per-transaction ceiling, paired with relatively conservative reserve rules. Overseas stablecoins undergo rigorous equivalence reviews and face narrow access channels. Core regulatory priorities are safeguarding redemptions and protecting user funds; stablecoins are positioned strictly as a supplement to traditional payment systems. Both jurisdictions adopted preemptive legislation, mandate full reserve backing, and require monthly reserve disclosures; however, Japan enforces stricter reserve controls, allowing a maximum 50% allocation to short-term government bonds.
- United States: The federal GENIUS Act framework developed later. Issuers include bank subsidiaries and compliant non-bank entities, resulting in a broader pool of eligible issuers and no per-transaction caps. Reserves may consist of highly liquid US Treasury securities, and reserve interest can be leveraged to support commercial models. State-level regulation runs in parallel, granting greater room for market innovation. Regulatory objectives center on preserving the global status of the US dollar while balancing innovation and risk.
Use Cases
- Japan's deployments: focus heavily on B2B corporate settlement, cross-border payments for inbound tourists, and retail pilots at convenience stores. All use cases aim to reuse existing POS and QR payment infrastructure without a radical overhaul of underlying systems. Programmable functions, agent payments, and tokenized assets remain in limited pilots.
- US stablecoins: cater to a more diverse range of crypto-native use cases: on-chain DeFi, RWA tokenization, AI agent payments, cross-border remittances, and retail payments are advancing in parallel. Stablecoins act as the foundational base money for the native blockchain ecosystem, driving faster iterative innovation.
Domestic Yen Stablecoin Growth: JPYC and JPYSC
- JPYC: JPYC Inc. registered as a Class 2 Fund Transfer Service Provider in August 2025 and formally launched its yen stablecoin on October 27, 2025, backed by yen deposits and Japanese government bonds. As of September 18, 2026, the cumulative issuance of JPYC EX surpassed JPY 10 billion. After listing on South Korea's Upbit exchange, its circulating supply peaked at JPY 4.29 billion before settling at JPY 3.88 billion on September 28. In August 2026, JPYC completed a JPY 6 billion Series B financing round, with logistics firm Maruwa investing JPY 1 billion in the capital increase.
- JPYSC: SBI Shinsei Trust Bank rolled out the trust-based yen stablecoin JPYSC in June 2026. By the end of September, the total yen stablecoin supply stood at approximately JPY 25 billion, of which JPYSC accounted for JPY 20 billion.
Access to Overseas Stablecoins
Starting in March 2025, Japanese users gained access to USDC via SBI VC Trade, marking it as the primary compliant offshore stablecoin available locally.
B2B Logistics Use Case: Alleviating Cash Flow Pressures for Subcontractors
The logistics sector has emerged as the most prominent B2B use case for stablecoin settlements.
- Industry pain points: AZ-COM Maruwa is a key same-day delivery partner for Amazon Japan, reporting JPY 230.5 billion in revenue for FY2026. Its network of roughly 2,300 small subcontractors and individual operators faces cash flow strains, driving demand for biweekly or even three settlements per month.
- Friction in conventional bank transfers: Average bank transfer fees reach JPY 160, and charges from regional credit unions can climb to JPY 800, imposing heavy costs for high-frequency settlements.
- JPYC Solution: On July 22, 2026, AZ-COM Maruwa took a strategic equity stake in JPYC, acquiring a 2.9% voting interest. It plans to roll out JPYC settlement for partner merchants in Tokyo in phases by year-end.
- Target: Shorten the settlement cycle to within five days after the cut-off date (e.g., payments completed by month-end for transactions closing on the 25th of each month).
- Corporate commentary: Company spokesperson Okamoto stated that JPYC is being adopted primarily to accelerate fund disbursements, not to reduce subcontractor compensation. President Washimi Katsumi remarked: "Settlement is social infrastructure. Industries thrive only when funds circulate smoothly."
III. Consumer-Facing Segment: Offline Retail and Cross-Border Payments for Visitors
C2B Retail Payments: From Airport Pilots to Direct POS Integration
Stablecoin retail payments have evolved from closed small-scale trials to point-of-sale (POS) QR code settlements.
Deployment roadmap: Airport/pop-up pilots → POS barcode payments → Nationwide QR network
(Haneda Airport T3 / Shibuya Pangea Café) | (Lawson POS integration) | (Binance Pay + PayPay)
Pilot milestones:
- Haneda Airport Trial: Netstars ran USDC payment trials at two Haneda T3 outlets from January 26 to February 28, 2026.
- Shibuya Café Pilot: Digital Garage, JCB, and Resona Bank hosted public USDC and JPYC trials at Pangea Café from February 24 to March 2.
- Aggregated Merchant Platform: On July 13, Netstars launched Stablecoin Pay, supporting USDC, USDT, and JPYC. Merchandise pricing and merchant settlements are denominated in yen with a 0.98% fee rate.
Landmark Lawson Convenience Store POS Pilot:
- Lawson Takanawa Gateway Store: Trials kicked off on August 6, 2026. Existing POS terminals scan barcodes from HashPort wallets to execute JPYC payments; stores do not need to manage crypto wallets independently.
- Osaki Gate City Store Expansion: The pilot was extended on August 17 with MetaMask wallet support for JPYC, USDC, and USDT.
Industry perspectives and roadmap:
At an industry forum on October 1, Taro Tamura of Lawson commented that processing direct stablecoin transactions through existing POS systems marks a first in Japan. Convenience stores represent the most promising channel for JPYC to enter everyday retail payments. Current technical optimizations aim to achieve transaction speeds comparable to domestic e-money services like au PAY.
Risuke Shimizu confirmed that data interfaces between POS registers and the blockchain payment layer are now aligned, and refund workflows have been fully designed. Hiroshi Yoshida, Chairman of HashPort, outlined the next phase: inbound tourists will be able to choose between credit cards and stablecoins at checkout.
Cross-Border Payments for Inbound Tourists: Nationwide QR Network Activated
On September 30, 2026, stablecoin retail payments expanded further for visitors.
- Payment rails: Binance Pay connects to PayPay's vast merchant network via the HIVEX cross-border gateway.
- User experience: KYC-verified overseas tourists scan PayPay QR codes at merchant outlets or present dynamic Binance Pay payment codes to settle purchases.
- Merchant side: Merchants receive settlement funds in yen and bear no crypto-asset exposure or risks.
- Coverage: The integration reaches millions of offline merchants and serves approximately 48 million Binance Pay users across more than 100 countries (note: Japanese residents currently cannot use this channel).
IV. Summary and Outlook
Japan is the world's first country to introduce dedicated stablecoin legislation, yet its commercial adoption trails behind the United States, Singapore, and other economies.
Key limiting factors:
- Relatively conservative regulatory frameworks restrict domestic issuers to banks, trust firms, and Class 2 Fund Transfer Service Providers, narrowing overall market participation.
- Former reserve rules requiring full deposit placement, compounded by prolonged low interest rates, limited reserve yields and weakened issuer promotion incentives.
- The JPY 1 million per-transaction cap for Class 2 licenses forces split processing for large corporate B2B payments, raising implementation costs. However, the June 2026 reserve reform permitting up to 50% allocation to short-term government bonds, paired with Japan's recent rate hikes, has partially improved issuer profitability.
Future trajectory: Japan will not relax its stablecoin rules aggressively. The core approach is to layer stablecoin capabilities on top of established traditional financial infrastructure. B2B corporate settlement (specifically logistics subcontractor payments) will be prioritized for scaling. On the retail side, by leveraging convenience store POS systems and PayPay QR networks, services will initially cater to inbound tourist cross-border payments. In the near term, tokenized assets and AI agent payments will remain confined to testnet PoC validations, reflecting persistent regulatory caution regarding programmable funds and open smart contracts, where redemption security remains the absolute priority.
From small-scale trials at Haneda Airport to live POS deployments at Lawson; from 2,300 logistics subcontractors to millions of PayPay offline merchants, Japan's stablecoin ecosystem is steadily penetrating the real economy by leveraging mature checkout, POS, and QR payment infrastructure. Merchants maintain yen-based accounting, while enterprises and consumers benefit from faster fund turnover and lower cross-border payment friction. With the validation of key pilots wrapping up by late 2026, Japan's stablecoin market is transitioning from feasibility testing to full-scale commercial operations.
References
- NADA NEWS (August 20, 2026) | Interview with Maruwa executives and communications team covering the AZ-COM Maruwa JPYC settlement project: https://www.nadanews.com/364700/
- Nikkei / CoinDesk (July 20, 2026) | Amazon Japan partner AZ-COM Maruwa to adopt yen stablecoin JPYC for subcontractor settlements: https://www.coindesk.com/business/2026/07/20/amazon-japan-supplier-az-com-maruwa-to-adopt-yen-stablecoin-jpyc-for-subcontractor-payments
- The Block (July 19, 2026) | Japanese logistics firm to deploy JPYC stablecoin for subcontractor disbursements: https://www.theblock.co/news/markets/2026-07-19-japanese-logistics-firm-to-use-jpyc-stablecoin-for-subcontractor-payments
- Digital Garage (February 19, 2026) | JCB and Resona Bank run public USDC and JPYC retail payment trials at a café: https://www.garage.co.jp/en/pr/release/20260219/
- Netstars (December 23, 2025) | Announcement of Japan's first in-store stablecoin USDC payment pilot at Haneda Airport T3, running Jan 26-Feb 28, 2026: https://netstars.co.jp/en/2025/12/23/launch-of-japans-first-in-store-payment-using-stablecoin-usdc-at-haneda-airport/
- HashPort (August 6, 2026) | Lawson Takanawa Gateway stablecoin POS pilot announcement: https://hashport.io/news/lawson2
- The Block (July 12, 2026) | Lawson partners with KDDI and HashPort to test JPYC stablecoin: https://www.theblock.co/news/business/2026-07-12-lawson-to-test-jpyc-stablecoin-with-kddi-hashport
- CoinPost (October 2, 2026) | Roundtable transcript featuring Taro Tamura, Risuke Shimizu, and Hiroshi Yoshida: https://coinpost.jp/?p=740431
- PayPay (September 30, 2026) | Binance Pay connects to PayPay via HIVEX, launching stablecoin payments for inbound tourists: https://about.paypay.ne.jp/pr/20260930/01/
- Cointelegraph (September 30, 2026) | PayPay merchants enable stablecoin payments via Binance Pay
- DigiFT (July 15, 2026) | SBI, DigiFT, and Startale announcement for JPYSC tokenized securities testing
- Financial Services Agency of Japan | 2022 Revised Payment Services Act, stablecoin legislative documents